If you've been watching the Grand Forks market from the sidelines, here's what you need to know heading into summer: this market is not cooling down — it's speeding up.In May 2026, 59 homes

Dated: March 30 2022
Views: 47
Based on the Primary Mortgage Market Survey from Freddie Mac, the average 30-year fixed-rate mortgage has increased by 1.2% (3.22% to 4.42%) since January of this year. The rate jumped by more than a quarter of a point from just a week ago. Here’s a visual to show how mortgage rate movement throughout 2021 was steady compared to the rapid increase in mortgage rates this year:
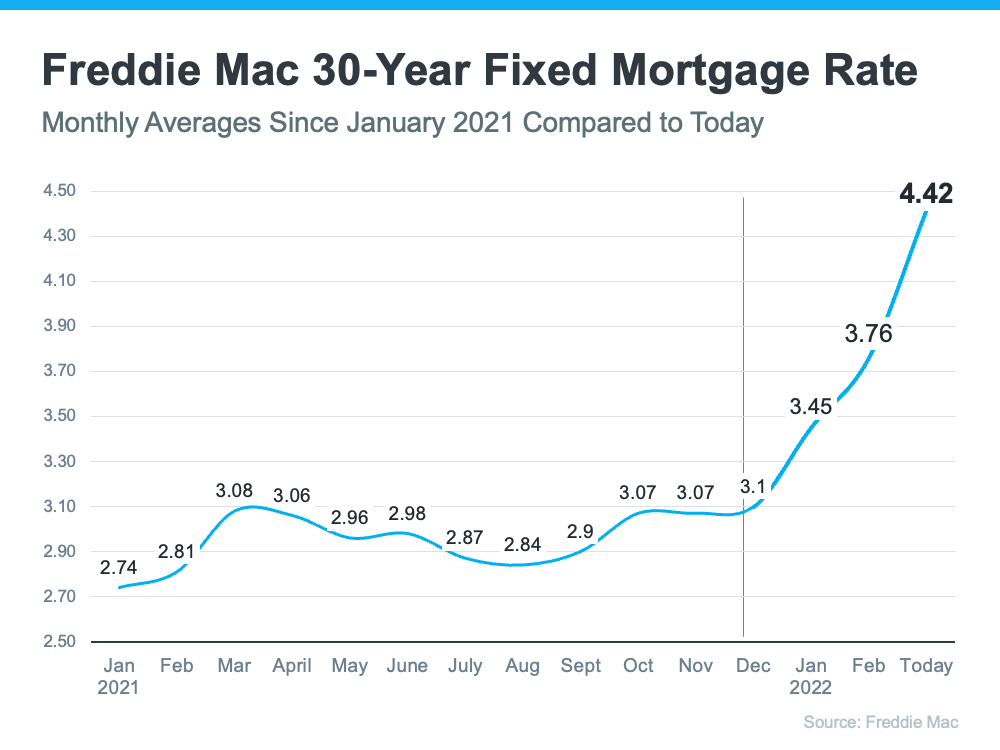
Just a few months ago, Freddie Mac projected mortgage rates would average 3.6% in 2022. Earlier this month, Fannie Mae forecast mortgage rates would average 3.8% in 2022. As the chart above shows, rates have already surpassed those projections.
Sam Khater, Chief Economist at Freddie Mac, explained in a press release last week:
“This week, the 30-year fixed-rate mortgage increased by more than a quarter of a percent as mortgage rates across all loan types continued to move up. Rising inflation, escalating geopolitical uncertainty and the Federal Reserve’s actions are driving rates higher and weakening consumers’ purchasing power.”
In a recent article by Bankrate, several industry experts weighed in on where rates might be headed going forward. Here are some of their forecasts:
“With inflation figures continuing to surprise to the upside, mortgage rates will remain above 4.0% on the 30-year fixed.”
“While higher short-term interest rates will push up mortgage rates, I expect some of this impact to be mitigated eventually through lower inflation. Thus, I expect the 30-year fixed mortgage rate to continue to rise, although we aren’t likely to see the big jumps that occurred over the past few weeks.”
“Mortgage rates are likely to continue to move higher throughout the balance of 2022, although the pace of rate increases is likely to moderate.”
In a recent realtor.com article, another expert adds to the conversation:
“. . . As markets digest the Fed’s updated economic projections, I anticipate a continued increase in mortgage rates over the next several months. . . .”
With both mortgage rates and home values expected to increase throughout the year, it would be better to buy sooner rather than later if you’re able. That’s because it’ll cost you more the longer you wait. But, there is a possible silver lining to buying a home right now. While you’ll be paying a higher price and a higher mortgage rate than you would have last year, rising prices do have a long-term benefit once you buy.
If you purchase a home today valued at $400,000 and put 10% down, you would be taking out a $360,000 mortgage. According to mortgagecalculator.net, at a 4.42% fixed mortgage rate, your mortgage payment would be $1,807 a month (this does not include insurance, taxes, and other fees because those vary by location).
Now, let’s put that mortgage payment into a new perspective based on the substantial growth in equity that comes with the escalation in home prices. Every quarter, Pulsenomics surveys a panel of over 100 economists, investment strategists, and housing market analysts about their expectations for future home prices in the United States. Last week, Pulsenomics released their latest Home Price Expectation Survey. The survey reveals that the average of the experts’ forecasts calls for a 9% increase in home values in 2022.
Based on those projections, a $400,000 house you buy today could be valued at $436,000 by this time next year. If you break that down, that means the equity in your home would increase by $3,000 a month over that period. That’s greater than the estimated monthly payment above. Granted, the increase in your net worth is tied to the home, but it is one way to put the home price appreciation to use in a way that benefits you.
Paying a higher price for a home and a higher mortgage rate can be a difficult pill to swallow. However, waiting will just cost you more. If you’re ready, willing, and able to buy a home, now will be a better time than a year, or even six months from now. Let’s connect to begin the process today.

In the dynamic world of real estate in Grand Forks, North Dakota, Josh Steinke stands out as a realtor with a deep connection to the community and a profound understanding of the local property market....
If you've been watching the Grand Forks market from the sidelines, here's what you need to know heading into summer: this market is not cooling down — it's speeding up.In May 2026, 59 homes
By Josh Steinke | Berkshire Hathaway HomeServices Family Realty 701-741-1335 | joshsteinke.grandforksfamilyrealty.comIf you've been thinking about buying or selling a home in Grand Forks or East
If you've been thinking about buying or selling a home in Grand Forks or East Grand Forks, here's the honest truth: the spring market is not waiting around.I've been watching this market closely,
Spring has arrived in Grand Forks — and so has a wave of real estate activity. If you've been thinking about buying or selling, here's an honest look at what the market is doing right now and
 Tax and special assessment figures are provided by the listing companies and are usually from the most recent tax bill, but buyer should verify amounts with appropriate governmental departments for accuracy and future estimates. New construction listings often have incomplete or no information on tax or special assessment estimates provided by listing companies, so they must be verified. Figures do not reflect any pending, proposed, or future special assessments which may be levied by governmental
bodies.
Information is submitted by member companies of the Fargo-Moorhead Area Association of REALTORS®.. All information provided is from sources believed to be reliable, but is not guaranteed and should be independently verified. No reproduction, distribution, or transmission of the information at this site is permitted without written permission from Berkshire Hathaway HomeServices Family Realty - Grand Forks.
Consumers should verify all information to consumer's own satisfaction before completing a purchase agreement in case of error, typographical or otherwise. Information is subject to change without notice.
The data relating to real estate for sale on this web site comes in part from the Broker Reciprocity Program of the Fargo-Moorhead Area Association of Realtors. Real estate listings held by brokerage firms other than Berkshire Hathaway HomeServices Family Realty - Grand Forks are marked with the Broker Reciprocity logo and detailed information about them includes the name of the listing brokers.
Show More...
 Grand Forks Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Berkshire Hathaway HomeServices Family Realty - Grand Forks may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 24, 2026 9:19 PM UTC
Show More...
